


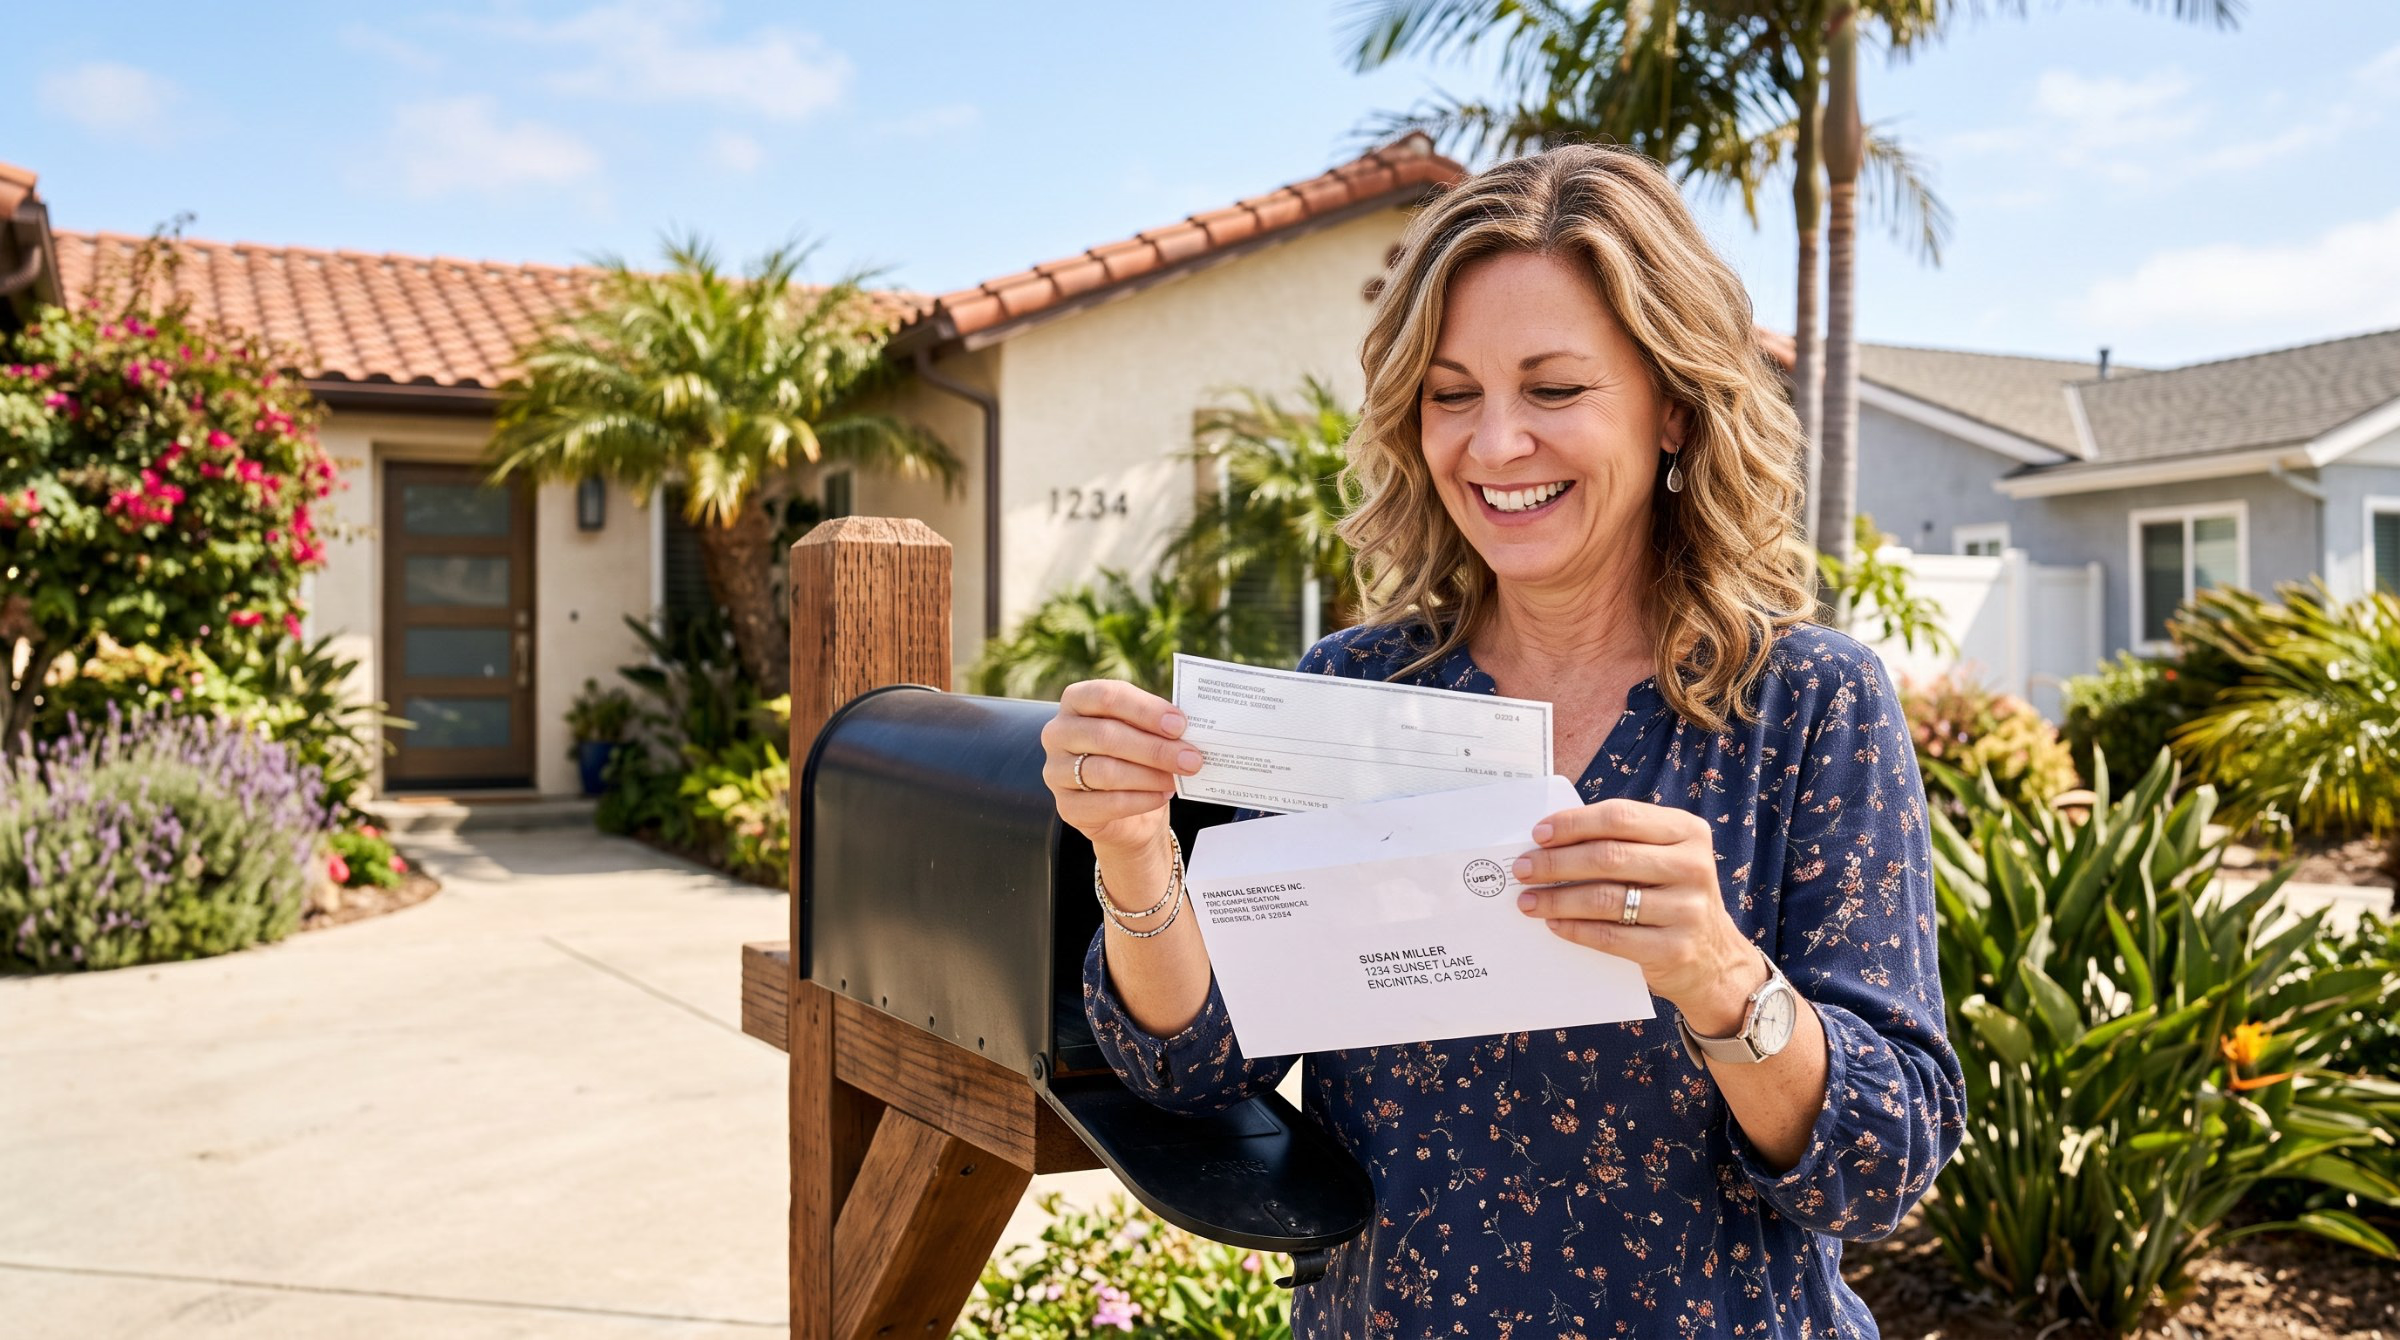
Escrow can feel confusing until you see it working in real life. During a home loan, the escrow account acts as the financial buffer that makes sure your property taxes and insurance premiums get paid on time. Most homeowners are familiar with the idea of making escrow payments as part of their monthly payment, but many are surprised when they receive an escrow refund check in the mail.
If you ever wondered what an escrow refund is, why it happens, how the timing works, or what to do with an escrow refund check you might have received, this guide breaks it all down. You will also learn how the timing works and how to use that money wisely during homeownership.
This is your full roadmap to understanding escrow refunds from start to finish.
How Mortgage Escrow Accounts Work
To understand escrow refunds, it helps to start with the basics. When you buy a home with a mortgage loan, part of your monthly payment is set aside to cover property taxes and homeowners insurance.
These funds go into an escrow account managed by your mortgage servicer/ mortgage lender or an escrow company and are used to pay your property tax payments, homeowners insurance premiums, and sometimes mortgage insurance or similar housing-related bills.
- Monthly Mortgage Payment - Your monthly payment usually includes principal (paying down the loan), interest, and an escrow payment portion. For example, a typical payment might say: 1/12 of property taxes, 1/12 of homeowners insurance premium, plus any mortgage insurance (PMI) if required.
- Escrow Account Management - Your mortgage servicer takes the tax and insurance portions and deposits them into your escrow account. When your tax bill or mortgage insurance premium is due, the servicer pays the bill on your behalf from those funds.
- Annual Escrow Analysis - Each year (or when you change loans), the servicer reviews all deposits and payments in the escrow account. They compare the total collected to the actual bills paid, plus a mandatory cushion (typically up to two months’ worth of escrow payments). The target balance for an escrow account is designed so that even after paying all upcoming bills, there is a small cushion remaining.
- Adjusting Your Payments - If the analysis shows you collected too little (a shortage), the lender will typically adjust your payment upward or ask for a lump-sum contribution over the next year to cover the shortage. If there’s extra money (a surplus), the lender must refund it to you, as long as the surplus is at least $50.
This system is governed by RESPA and enforced by the Consumer Financial Protection Bureau (CFPB). For example, CFPB guidance notes that servicers must send borrowers an annual escrow statement within 30 days of year’s end, showing all escrow activity and any shortage or surplus.
By law, surpluses of $50+ must be refunded within 30 days of the escrow analysis. In practice, the time it takes to receive the check can be a bit longer (usually 30-60 days after year-end) due to processing and mail time.
Written by Lightspeed EscrowLicensed escrow company in Covina, CA
 Start your escrow
 Licensed by the California DFPI